91-9711165183
 October 6, 2026
Looking to renovate his home before the festive season, Rahul applied for a personal loan. With a secure job and a consistent credit rating, he was surprised to be denied a personal loan. Upon further inquiry, he was told the culprit was the app loans he had taken out recently to cover travel expenses. This is now a familiar scenario for salaried people who have taken funds through digital apps.
Digital lending apps, regulated by the RBI (Reserve Bank of India) and introduced to encourage lending, are fast becoming the most popular way for salaried people to get funds, as they process loans with a click and minimal checks. This advantage is now driving debt: getting funds seems easy, but people pay little attention to terms and costs, driven by the instant gratification of approval.
Personal loans from apps are unsecured loans issued for a limited term through a digital interface, such as a mobile phone, from the comfort of your home or on the go. With digital identity verification and e-KYC, app loan lenders disburse funds within minutes after an online check of your CIBIL score and creditworthiness.
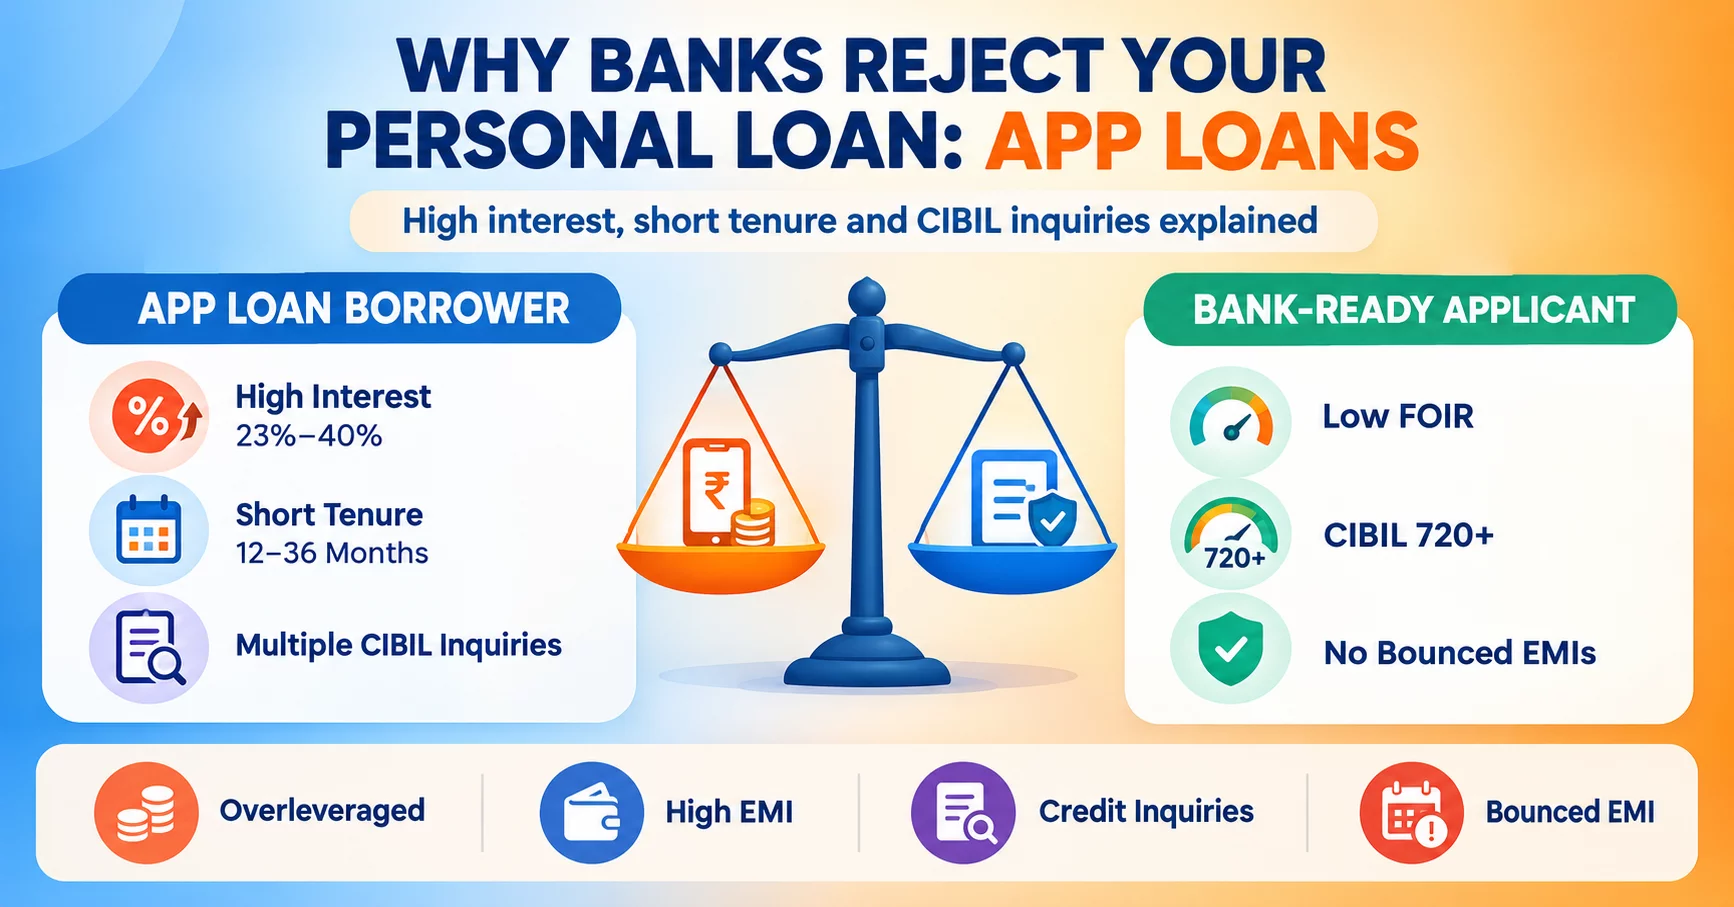
App loans are now a major reason for personal loan rejection in India. At first, an app loan was meant to bridge funding shortfalls until the salary was credited, like payday loans, but as customers got used to an easy source of funds, they were tempted to use app loans frequently. Personal loan requests from applicants using app loans are now being rejected due to the following:
High interest rates can make the repayment unaffordable, putting pressure on the budget. When accepting app loan funds, applicants pay little attention to costs such as interest rates and processing fees. Interest rates for app loans start at 23%, with a 5% processing fee deducted on disbursal.
High app loan costs can delay repayment; a bounced EMI in the last 3 months of your loan will lead to rejection of your personal loan.
App loans have a repayment term of 12 to 36 months, which may strain the applicant’s monthly budget. The short repayment tenure of existing app loans indicates higher risk for banks, which value a longer on-time repayment track record before issuing further funds as unsecured personal loans.
A restricted tenure, coupled with a high interest rate on an app loan, results in a higher monthly EMI that exceeds the allowed monthly FOIR (Fixed Obligation to Income Ratio). The FOIR indicates the amount of funds an applicant can allocate to debt after covering monthly expenses.
Banks usually allot 50% to 70% of the income towards credit; an applicant earning a higher income of, say, ₹80,000 can allot a higher ratio of the income towards debt as compared to an income of ₹40,000.
Example:
With the current debt, the applicant’s FOIR is nearly exhausted. The applicant’s request for a further personal loan is denied as “customer is overleveraged“.
Each time an applicant applies for credit, the lender forwards an inquiry to CIBIL. The inquiries are noted in the CIBIL record, reducing the CIBIL score by a few points with each inquiry; individuals applying for app loans have an excess of inquiries, which classifies them as credit-hungry.
Applicants are ineligible for an ICICI Bank personal loan as per policy if they have made more than 5 credit inquiries in the past 3 months.
App loan users often take out small loans frequently to tide over financial shortfalls, without realizing that the ease with which funds are disbursed may come at a high cost and that the debt can multiply significantly. Banks look at the outstanding balance of app loans and the inflated EMI to be paid, and deny a personal loan on eligibility grounds.
Arun came to us extremely distressed; he had taken a number of app loans to meet emergency requirements of his father’s sudden hospitalization. He needed the funds urgently, and with the app loans, he got them instantly. Under pressure to pay for the treatment, he repeatedly took out app loans. His profile and obligations are as follows:
If Arun had applied for a personal loan prior to the app loans, he would have been eligible for a personal loan of ₹10,00,000 as per the multiplier applied to a CAT B company for HDFC Bank personal loan eligibility. (Figures are indicative; final eligibility is as per the bank’s policy.) But given the high interest rates and short tenures of his app loans, he could not qualify for a personal loan.
A personal loan from banks differs from an app loan issued by fintechs in policy, terms, and process.
| Parameter | Banks | Apps |
|---|---|---|
| Personal loan interest rate | 9.99% to 24% | 23% to 40% |
| Processing fees | 1% to 2.5% | 3% to 5% onwards |
| Loan amount | ₹50,000 to ₹50 lakhs | ₹10,000 to ₹5 lakhs |
| CIBIL score | 720+ | 620+ |
| Tenure | 12 to 72 months | 1 to 36 months |
| Process time | 24 to 72 hours | Instant processing |
There is no rule that you will not get a personal loan approval if you are running an app loan, but there are some established patterns of app loan users that make banks wary. If you are running an app loan, you need to do the following:
In our experience, we have noted that app loans soon become a habit: the initial one is taken until you receive your next salary or in an emergency. Before you know it, you are taking out your next app loan to repay the previous loan EMI. Therefore, banks now consider applicants with app loans to be high risk for unsecured personal loans. Next time, before you click on that instant loan app, take a minute to check how much that loan will cost you, as the quick funding can make you ineligible for further credit.
Looking for the best option for unsecured funds? Our experienced advisors are happy to guide you. Our services are free of cost.
App loans can cost you a personal loan rejection as:
Over time, as app loan usage has increased, user track records show that lenient lending has led customers to accumulate numerous app loans and high debt. Customers with as many as 15 to 20 app loans have contacted us seeking a solution; one or two app loans with an affordable EMI and a low principal balance are acceptable to banks. But personal loan applicants with multiple app loans, even with a 750+ CIBIL score, will be rejected.
Personal loans are allotted to applicants having an app loan as per the following criteria:
If you have been able to successfully close your app loans, the interval before applying for a personal loan depends on the following: